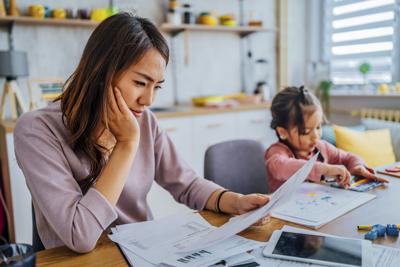

Young stressed mother checking her finances while her daughter is playing next to her
Nearly one in four American parents — 24% — saw their monthly household spending increase by $1,000 or more after having children. That figure is not a projection or a worst-case estimate. It is what actually happened to a significant share of families once a child arrived. For many households, the financial shift came fast and without much warning, and the numbers suggest that most parents were not prepared for how steep or how immediate that shift would be.
Understanding where that money goes, and why so many families end up scrambling to keep up, is genuinely useful for anyone who is planning for children or already adjusting to life with a new one.
Where the Extra $1,000 Actually Goes
When parents are asked what costs the most after having a child, two categories dominate: food and household goods, cited by 38% of respondents as their top expense, and childcare, cited by 29%. Together, those two categories explain most of the monthly increase that catches families off guard.
People are also reading…
What makes this harder to plan for is that neither category behaves like a single, predictable line item. Food and household costs expand gradually across dozens of small purchases — formula, diapers, wipes, baby food, and then eventually snacks, clothing, and a steady rotation of items that get outgrown. Childcare, by contrast, tends to arrive as a fixed and substantial monthly bill that does not flex based on what else is happening in the budget.
According to Rocket Mortgage's findings on the cost of parenting, 67% of parents say raising children has cost more than they expected — with 38% saying it has cost "much more." That is not a story about a few people who under-budgeted. It is a pattern that holds across a broad cross-section of American families.
Food and Household Goods: The Accumulating Daily Cost
The reason food and household goods land at the top of the list is partly obvious and partly easy to underestimate. A newborn requires a significant ongoing supply of consumables. Formula alone can run $150 to $300 a month depending on the brand and the baby. Diapers and wipes add another $80 to $150 per month on average. Those costs are front-loaded in the early months, when parents are also dealing with reduced income in some cases, new insurance costs, and the one-time purchases that come with setting up for a baby.
What families often miss in their pre-baby budgeting is how these daily costs layer on top of each other. It is rarely one large purchase — it is dozens of mid-sized ones that reset every month. Grocery bills may go up even when the baby is not eating solid food yet, because caregivers may be home more, routines shift, and convenience spending tends to rise when sleep is limited and time is short.
By the toddler years, food costs stay elevated while clothing, activities, and educational materials start adding in. There is no point in the first several years when this category meaningfully shrinks.
Childcare: The Fixed Monthly Pressure
Childcare is where the budget shock tends to be sharpest. Fifty-four percent of parents surveyed currently pay for childcare, and among those who do, 32% are spending between 20% and 29% of their total household income on it. Child Care Aware of America's research consistently places average annual childcare costs above $10,000 in most states, and in high-cost metros, center-based infant care can exceed $20,000 per year.
Unlike food and household goods, childcare is not something most families can gradually adjust to. It typically starts the moment a parent returns to work, which is often within weeks or months of birth, and the cost stays fixed regardless of whether anything else in the budget is straining. Families cannot skip a childcare payment the way they might delay a discretionary purchase.
This fixed quality is exactly what makes childcare one of the harder costs to absorb. When 32% of household income is committed before any other bills are paid, the margin for everything else compresses significantly. Groceries, utilities, car payments, and savings contributions all have to fit into what remains.
Why Families Still Get Caught Off Guard
Given how widely this information is available, the persistence of budget shock among new parents is worth examining. The survey data offers a few clues.
First, pre-baby budgeting often focuses on the visible, one-time costs: a crib, a stroller, a car seat. These are concrete items that can be priced out in advance. The recurring costs — particularly childcare and consumables — are harder to visualize until they are actually happening, and their combined weight often exceeds what families estimated for the tangible gear.
Second, the emotional and logistical pressure of early parenthood makes reactive spending more likely. When a parent is exhausted, returning to work, and trying to manage a household with a newborn, the path of least resistance may involve spending money to reduce friction. That is not irrational, but it does push costs higher than any pre-baby spreadsheet accounted for.
Third, the consequences are real and lasting. Fifty-eight percent of parents have gone into debt — through credit cards or loans — specifically for child-related expenses. Half of all parents in the survey said financial concerns led them to delay or decide against having additional children. These are not marginal outcomes. They reflect how deeply the cost reality diverges from expectations for a substantial share of American families. The strain is persistent rather than occasional, too: 46% of parents said child-related finances cause them stress always or usually. And the pressure reaches well beyond the monthly budget — 26% of parents have cut back on savings or investments and 14% have reduced their retirement contributions to keep up, trading long-term financial goals for short-term cash flow.
The most recent federal benchmark comes from the U.S. Department of Agriculture's 2015 report on family expenditures, which found that middle-income families spent about $12,980 per child that year. The USDA discontinued the series after that report, but more current data from Child Care Aware of America shows that childcare — one of the largest components of that figure — has kept climbing in the years since.
Planning does not eliminate these costs, but it changes how families absorb them. Knowing that food and household goods and childcare will likely drive the bulk of the increase — and building those recurring costs into the budget before the baby arrives rather than after — gives families a more accurate picture of what the first year actually looks like. It also makes the larger decisions that often follow a new child easier to weigh, from building a savings cushion to considering the long-term stability of homeownership — choices that may be more manageable with flexible financing options and a clear plan than under pressure.